Nonprofit Financial Hub
CD-Secured Loan or Line of Credit: How Nonprofits Should Decide
CD-Secured Loan or Line of Credit: How Nonprofits Should Decide
A CD-secured loan and a cash-secured line of credit both let a nonprofit borrow against money it already holds, without breaking a certificate of deposit early or liquidating a reserve fund. The two structures solve different problems. One hands over a fixed amount on a set repayment schedule. The other opens ongoing access to funds that a nonprofit draws only when needed.
Picking the wrong one can mean paying interest on money that sits unused, or reapplying for a new loan every time a cash gap reopens. Here’s how a CD-secured loan differs from a cash-secured line of credit, and which situations tend to favor each one.
What Is a CD-Secured Loan?
A CD-secured loan lets a nonprofit borrow against the value of a certificate of deposit it already holds, using the CD itself as collateral rather than pledging receivables, equipment, or real estate. It falls inside the same family as other cash-backed loans for nonprofits, where a lender advances funds against cash or a cash-equivalent holding instead of requiring a new asset pledge or a personal guarantee.
The CD-specific detail worth understanding is what happens to the certificate itself. In most CD-secured arrangements, the lender places a hold or assignment on the CD rather than cashing it out, so the certificate can continue toward its maturity date under its own terms while the loan runs alongside it. That single feature, borrowing without disturbing the CD’s term, is what separates a CD-secured loan from simply withdrawing the CD early and paying whatever penalty applies.
Nonprofits that hold operating reserves in CDs often did so deliberately, parking cash that isn’t needed immediately somewhere it earns a return instead of sitting in a checking account. A CD-secured loan is the option that lets that reserve keep doing its job while still functioning as a source of financing when a specific need comes up.
Because the loan amount is tied to one specific CD balance, it is structured as a single lump-sum disbursement with a fixed term, not a line a nonprofit can redraw. That structure is the starting point for the comparison below.
CD-Secured Loan vs. Cash-Secured Line of Credit
The two products differ less in what they’re secured by and more in how a nonprofit gets to use the money.
- How funds are accessed: a CD-secured loan pays out once, as a lump sum, at closing. A cash-secured line of credit opens a limit that a nonprofit can draw from repeatedly during an agreed period, in amounts it chooses.
- Repayment structure: a CD-secured loan is repaid on a fixed installment schedule that brings the balance to zero by a set date. A line of credit charges interest only on the amount actually drawn, and a nonprofit can repay and redraw within the same facility instead of applying for a new loan each time.
- Rate structure: because a lump-sum loan is tied to a single CD for a defined term and a revolving line is priced around ongoing access rather than a one-time balance, the two are structured differently for pricing purposes. Which one costs less in a given case depends on the lender, the size of the facility, and the terms of the CD or cash reserve involved, so this is worth confirming directly rather than assuming either structure is automatically cheaper.
- Predictable vs. variable needs: a lump sum works best against a cost that’s already known, since the loan amount is fixed at closing. A revolving line is built for needs that move around from month to month, where committing to one fixed number in advance would mean over-borrowing in some months and coming up short in others.
- Fit with planning: a lump sum lines up with a single, board-approved line item that already has a number attached to it. A revolving facility lines up with a standing need that finance staff monitor and draw against across a fiscal year.
When the Lump Sum Fits
A CD-secured loan tends to fit when a nonprofit already knows roughly how much it needs and when it needs it. If the expense is a single, predictable one, a facility deposit, a piece of equipment, or a bridge to one specific, dated payment, a lump sum that gets repaid on a fixed schedule is simpler to manage than a revolving balance that has to be tracked and rebalanced.
When Revolving Access Fits Better
A cash-secured line of credit tends to fit when the cash need repeats or the timing isn’t fixed. If a nonprofit expects to draw funds at different points across the year, rather than once, reapplying for a new lump-sum loan every time a gap opens is slower and more disruptive than drawing against a limit that’s already in place.
How Nonprofits May Use Each Structure
CD-Secured Loan Scenarios
A CD-secured loan tends to come up when a nonprofit is waiting on a specific grant disbursement and needs to cover a known amount until the payment lands, or when it’s committed to a planned capital or operating expense with a defined cost, such as a facility deposit or a piece of equipment approved in the current budget.
In each case, the organization already knows approximately how much it needs to borrow, which is what makes a single, fixed loan a workable fit. Nonprofits considering this route can review a cash-secured loan option to see how the structure applies to a defined, one-time need.
Cash-Secured Line of Credit Scenarios
A revolving facility tends to fit organizations with seasonal revenue, where most income arrives in one or two months but expenses continue year-round, or those with recurring timing gaps between when a program delivers services and when a grant or reimbursement actually pays out. It also suits a nonprofit that can’t yet size the expense precisely, since a line of credit only charges for what’s drawn rather than requiring the organization to commit to a fixed amount up front.
A nonprofit running several programs on different funding cycles may draw against the line for one program’s timing gap in the spring and a separate program’s gap in the fall, repaying each draw as the related revenue arrives rather than carrying one loan balance sized for the whole year.
What Determines Whether a CD Can Be Pledged
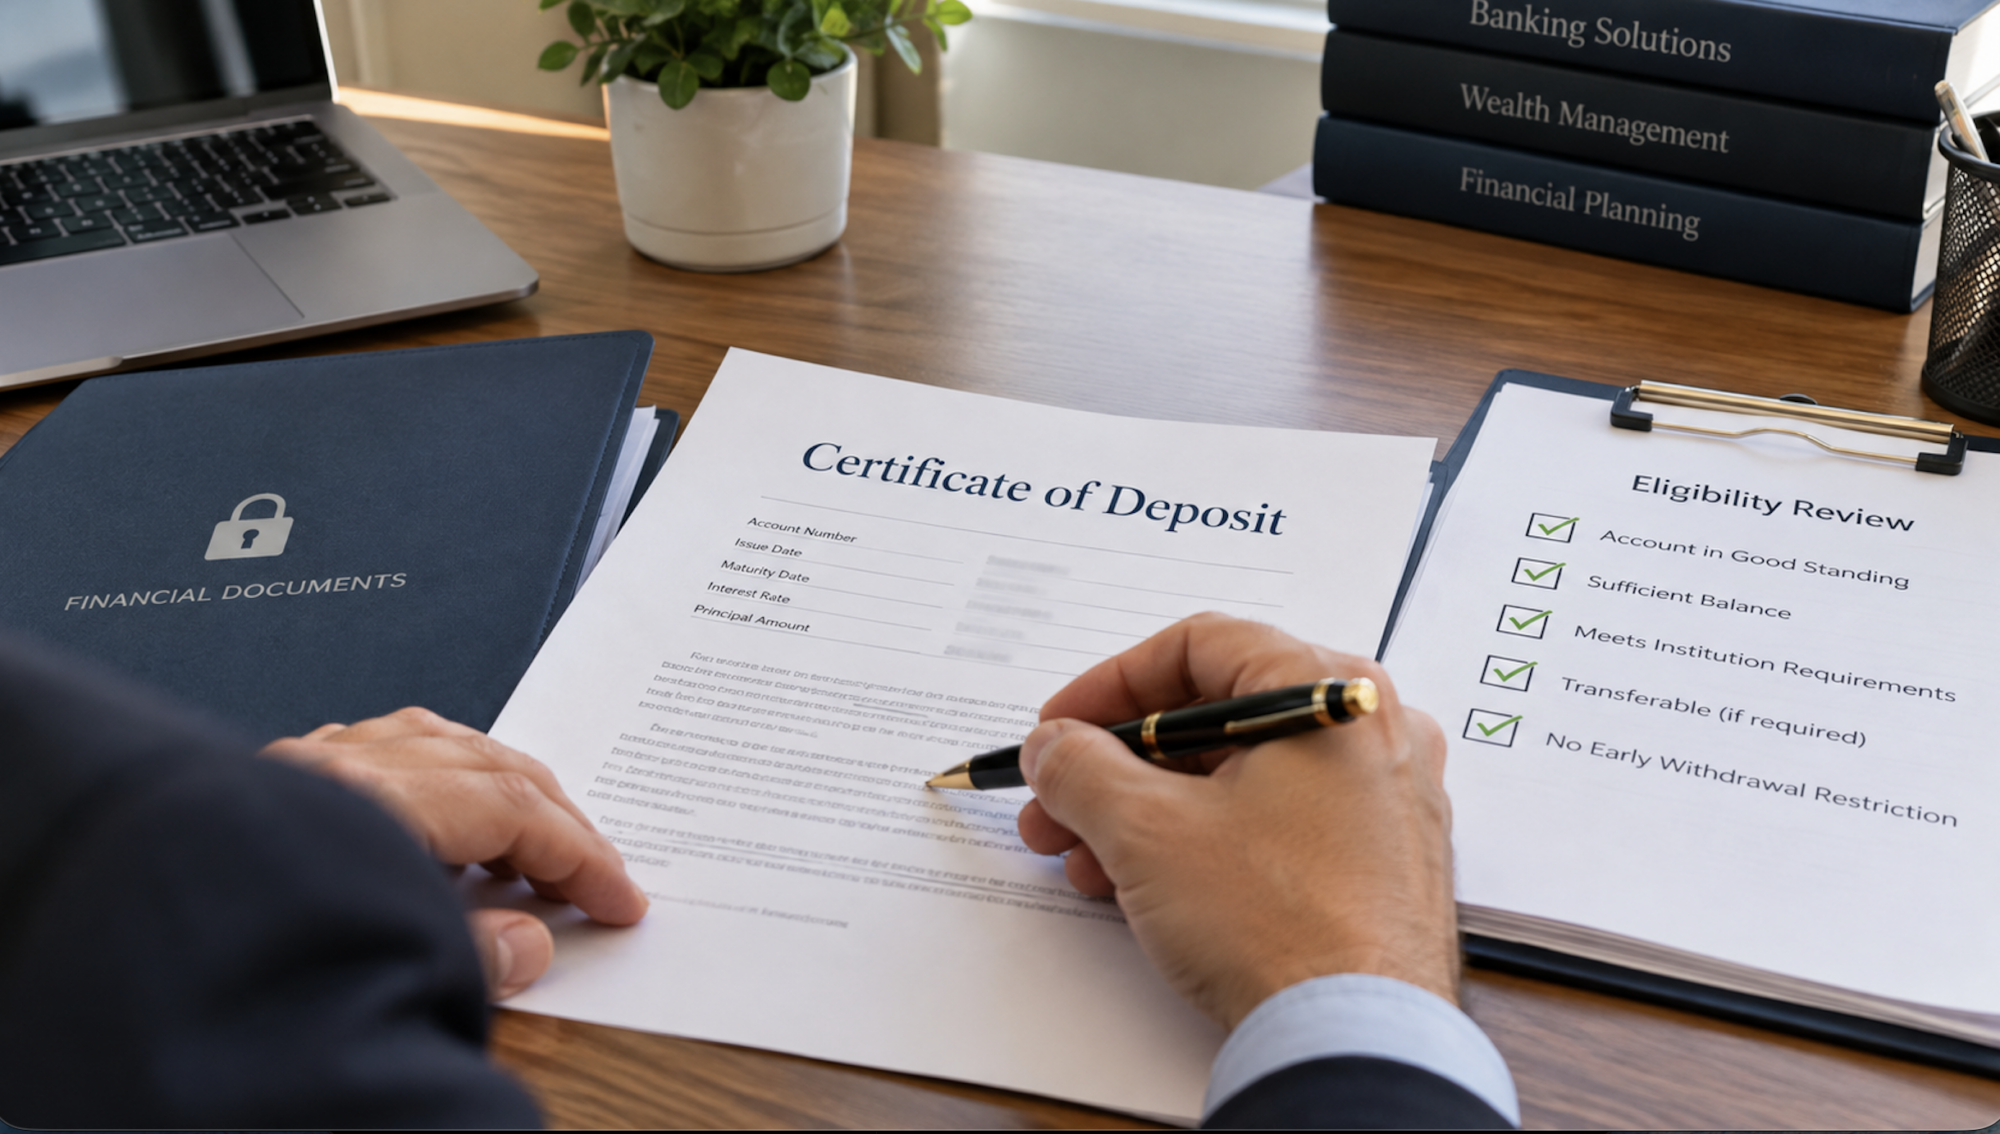
Not every certificate of deposit is automatically eligible to secure a loan, and the requirements that apply can vary by lender and by the terms of the CD itself. A few considerations tend to matter across most arrangements:
- Maturity date relative to the loan term: a CD maturing well before the loan is repaid may need to be renewed or replaced as collateral partway through, depending on how the lender structures the pledge.
- Ownership of the CD: the certificate generally needs to belong to the nonprofit itself, held in the organization’s name, rather than to an individual board member or a related entity.
- Restricted vs. unrestricted funds: if the CD holds donor-restricted money, pledging it as collateral may raise separate questions about whether that use is consistent with the restriction, and that determination typically involves the nonprofit’s own board or legal review rather than the lender.
- Whether the funds are actually available to pledge: a CD already serving as collateral for another obligation, or one held jointly with another party, may not be free to pledge again until that’s resolved.
- Early-withdrawal terms on the CD itself: a CD-secured loan is generally structured to avoid triggering the certificate’s own early-withdrawal penalty, since the CD isn’t being cashed out. Confirming that the pledge arrangement actually works that way, rather than assuming it, is part of reviewing the loan terms.
Because these requirements differ by lender and by the specific CD agreement in place, it’s worth confirming eligibility directly rather than assuming a given CD automatically qualifies.
Frequently Asked Questions
Can a nonprofit use a restricted-fund CD as collateral for a loan?
It depends on the terms of the restriction and the lender’s own policies. Because donor-restricted funds carry obligations beyond the nonprofit’s own discretion, this is generally a question to work through with the organization’s board or legal counsel before assuming a restricted CD is available to pledge.
What happens to the CD if the nonprofit can’t keep up with payments?
Since the CD secures the loan, a lender generally has the right to apply the pledged funds toward any unpaid balance. The exact process for doing so depends on the specific loan agreement, so it’s worth reviewing those terms closely before borrowing.
Is a loan against a CD structured the same way at every institution?
No. How a loan against a CD is documented, whether the CD must be held at the same institution making the loan, and how the hold or assignment is recorded can all differ by lender. These details are part of what to confirm before assuming any specific terms apply.
Does a nonprofit have to choose only one of these structures?
Not necessarily. Some organizations use a CD-secured loan for a known, one-time expense while keeping a separate cash-secured line of credit in place as a standing option for recurring or unpredictable gaps. The two aren’t mutually exclusive; they answer different kinds of cash needs.
Which option costs less, a CD-secured loan or a cash-secured line of credit?
There’s no universal answer. Pricing on either structure depends on the lender, the size and term of the facility, and the specific CD or cash reserve backing it. A nonprofit comparing the two is better served by requesting terms for its actual situation than by assuming one structure is inherently cheaper than the other.